

Score per company
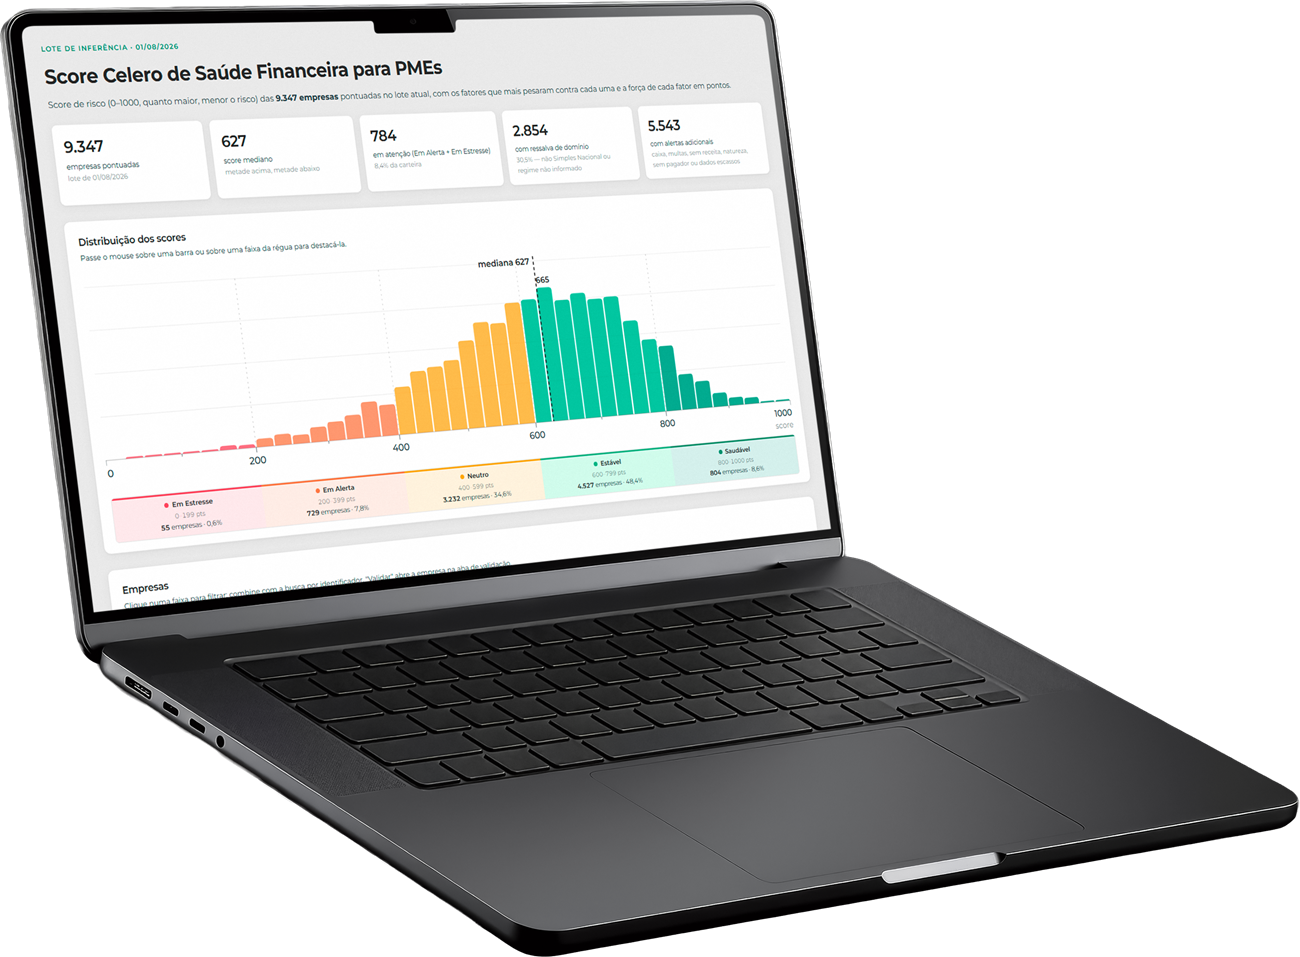
A 0 to 1000 rating, with the 3 factors that best explain it
Identify risks in your SMB portfolio, from default to commingled company and personal assets, and turn transaction data into intelligence for safer, more strategic decisions
Talk to usWithout context, assessing each company's risk takes more time and effort
Sources (Brazil data): BACEN · FGV · SEBRAE · PwC · McKinsey
A 0 to 1000 rating, with the 3 factors that best explain it
Companies distributed by risk band
Low-risk companies, ready for an offer
Companies showing signs of financial stress
Strengthen your credit policy with Celero Score. More information to decide with confidence, without giving up your institution's own criteria
Talk to usCelero is the first SMB data infrastructure in Latin America. With a proprietary foundation model, built on more than 10 years of experience with SMBs, we read companies' real account activity and give financial institutions a clear view of every SMB client in their portfolio.
It is a proprietary AI that has learned from more than 10 years of SMB transactions. It separates actual revenue from money that just passes through the account, such as loans, capital injections from partners or transfers between accounts of the same owner. It is the foundation on which Insights, Score and BFM are built.
From the institution's own full bank statements. It is data the institution already has, complete and historical, but cannot read today. We use no credit bureau or public data.
Yes. Processing takes place in a segregated environment, and the institution receives the reading per company, never a classified database. Your data never leaves home or becomes a third-party product.
No. Celero suggests, the institution decides. The reading adds to what your team and your models already do, without replacing them.
Each company's observed ability to pay, based on its real account activity. It helps you see deterioration before the first late payment.
No. It adds a layer no credit bureau has, and it is especially useful for new companies or ones the bureau barely sees.
The model depends on each institution's profile and project. The first step is usually a diagnostic on your own portfolio.